UM / UIM INSURANCE CLAIMS

Uninsured & Underinsured Motorist Lawyers

When the at-fault coverage is missing or too small, your own policy may become part of the recovery path.

Uninsured and underinsured motorist claims are first-party insurance claims tied to an underlying crash. They require both the ordinary liability and damages proof and a careful review of policy language, insured status, notice, consent, offsets, and state-specific coverage rules.
✓ Policies audited
✓ Notice protected
✓ Coverage sequencing mapped
WHY UM / UIM CLAIMS ARE DIFFERENT

The insurer may be your own carrier, but the claim can still involve contested liability, damages, and contract terms.

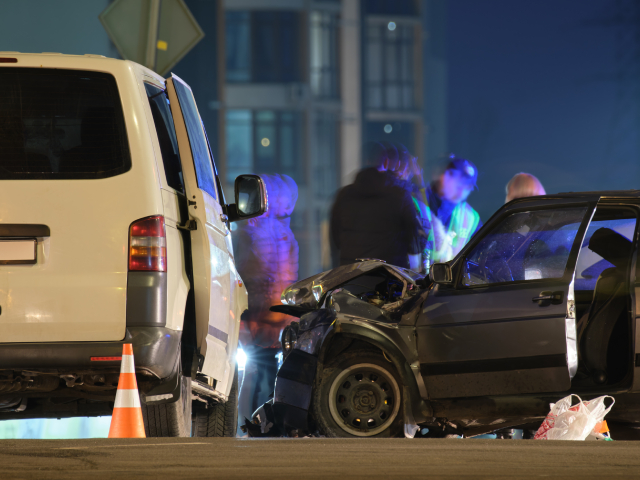
UM and UIM coverage can become important after an uninsured driver, hit-and-run, or crash where the responsible party’s liability limits are not enough. The exact path depends on the policy and governing law.

Uninsured motorist coverage

UM may respond when the responsible driver has no applicable liability insurance or in certain hit-and-run situations, subject to the policy and state law.

Underinsured motorist coverage

UIM may become relevant when the at-fault liability limits are insufficient to cover the supported losses and policy conditions are satisfied.

Who qualifies as an insured

Named insureds, household members, passengers, pedestrians, or occupants may have different potential coverage paths depending on policy language and jurisdiction.

Multiple policies and vehicles

More than one policy or vehicle can create stacking, priority, offset, or other coordination questions that cannot be answered without reviewing the actual contracts and law.
POLICY ANALYSIS & PRESERVATION

Collect the actual policies and endorsements before accepting a coverage position as final.

Declarations pages are useful, but the full contract, endorsements, correspondence, settlement requirements, and underlying crash evidence may all matter.

Documents that may matter

  • Declarations pages, full policies, endorsements, and renewal materials
  • Reservation-of-rights, coverage, and claim correspondence
  • At-fault liability limits and settlement documentation
  • Crash evidence proving fault and causation
  • Medical, wage, and damages records supporting claim value

Why sequencing matters

Some policies or state laws impose notice, consent-to-settle, subrogation, exhaustion, or other procedural requirements. Settling the liability claim without understanding those requirements can create avoidable disputes with the UM/UIM carrier.

HOW THE CLAIM IS BUILT

Build the underlying crash claim and the first-party coverage claim in the right sequence.

The insurer needs a supported liability and damages record, while the insured also needs to comply with the contract and governing law.
01

Audit every potentially relevant policy

Collect the contracts, endorsements, household and vehicle information, and identify who may qualify for coverage.
02

Protect notice, consent, and subrogation issues

Give appropriate notice and evaluate settlement or preservation requirements before resolving the at-fault claim.
03

Prove liability, causation, and damages

Develop the underlying crash evidence and document medical, wage, future-care, and human losses just as carefully as a third-party claim.
04

Resolve coverage and value disputes

Address limits, offsets, priority, stacking, insured status, valuation, and litigation when the policy or claim value remains disputed.
COVERAGE VALUE & NEXT STEPS

A policy limit is not the same thing as a claim value—and having coverage does not eliminate the proof requirements.

The recovery analysis has to compare the supported damages with the liability coverage already available and the terms, limits, and conditions of each potentially applicable UM/UIM policy.

Issues to document and calculate

  • Liability limits and amounts already paid or available
  • Medical expenses, future care, wage loss, and reduced earning ability
  • Pain, disability, and other recoverable human losses
  • UM/UIM limits, offsets, priority, stacking, and other policy-specific issues
WHAT TO DO NOW

Do not settle the underlying liability claim before checking UM/UIM requirements.

Some policies require notice, consent, preservation of subrogation rights, or other steps before settlement. The exact rules vary by contract and jurisdiction, so the sequencing should be reviewed before signing a release.
ATTORNEY-LED GUIDANCE

UM/UIM claims are part injury case and part insurance-contract analysis.

Carma Legal approaches UM/UIM matters by reviewing the potentially applicable policies, protecting procedural requirements, and building the same liability and damages proof required in the underlying collision claim. Representation depends on jurisdiction and licensure.
✓Direct attorney involvement
✓Clear next steps and communication
✓Case strategy built for negotiation and litigation
UM / UIM QUESTIONS

Questions that often arise when the at-fault insurance is missing or insufficient

Often the claims are coordinated rather than treated as either-or, but the correct sequence depends on the policies and state law. Consent, exhaustion, notice, and subrogation issues should be reviewed before settlement.
It can in many policies and jurisdictions, but requirements vary. Prompt reporting, crash documentation, witness or video evidence, and compliance with policy conditions can be especially important.
Potentially. Coverage can depend on the person’s own policy, household policies, the vehicle involved, insured-status definitions, and state law. All plausible policies should be identified and reviewed.
AUDIT THE COVERAGE

Before accepting that there is not enough insurance, identify every policy that may apply.

Share the crash information, at-fault insurance details, your auto policies, household coverage, insurer correspondence, injuries, and treatment so the coverage path can be evaluated.