A client texted me last Thursday from a CVS parking lot on East Boulevard asking if she should go back to work even though her orthopedist told her to stay home another two weeks. She had been off for twelve days, her manager was pressing her about when she would return, and the at-fault driver’s adjuster had just told her that lost income was “hard to prove” and that she should focus on her medical treatment instead. Here is what I told her, and what I want you to understand before you file a lost wages claim after a Charlotte car accident: that income may be recoverable, but only if you prove it the right way, in the right order, and at the right time. The adjuster is not going to help you build that proof. That part is on you, and it is exactly the part I take over for the people I represent at Carma Legal.
What Does a Lost Wages Claim Cover in North Carolina?
A lost wages claim covers the exact income you could not earn because you were treating your injuries or were physically unable to work after the crash. In Charlotte cases, that includes hourly pay, salary, commissions, bonuses you would have received during the missed period, and self-employment income if you can document it.
This is money separate from your medical bills, and people confuse the two all the time. Your medical bills are what the treatment cost. Your lost wages are what your injury cost you at work. They are two different columns on the same claim, and the at-fault driver’s insurer may owe you on both. Wage replacement is a recognized loss across nearly every injury compensation system. Workers’ compensation programs, for example, pay cash benefits to people who cannot work because of an injury, as USA.gov explains. A third-party car accident claim works on a similar principle: the income someone else’s negligence took from you may be money you are owed back.
I have spent twelve years practicing this work, I hold active licenses in both North Carolina and Nevada, and I have represented many clients, first inside large Las Vegas firms and then in the boutique setting I run now at Carma Legal. Keeping the firm small is a deliberate choice, so the person building your wage proof and negotiating it with the insurer is me, not a rotating cast of paralegals. When you call, you reach the attorney handling your file directly, by phone, text, or email.
Why Waiting Until Settlement to Mention Lost Time Can Be Costly
One common mistake I see Charlotte claimants make is waiting until settlement to bring up their lost time from work. By then the adjuster has already assigned a value to the claim, and late wage documentation gets treated as an afterthought rather than a real loss.
Think about it from the adjuster’s side. If wage loss shows up in the very first demand, backed by an employer letter and paystubs, it is baked into the number from day one. If it shows up two months later, after offers have already been exchanged, the adjuster sees it as a bolt-on, something you thought of at the last minute to pad the file. That skepticism can cost you money you actually lost.
That is why I request employer verification and paystub records at Carma Legal in the first weeks after intake, long before we are anywhere near a settlement conversation. I want the insurer to see documented wage loss as part of the opening demand, not a surprise at the end. Preparing the case from the beginning is not a slogan for me, it is how I keep the insurer from ever getting the chance to dispute a loss that was real. When you build the record early, you control the conversation. When you wait, the adjuster controls it.
Which Records Do You Need Before You Start?
Before you file, gather three things: your paystubs from the 90 days before the collision, your current employer’s contact information, and a record of any paid time off or sick leave you used to cover the days you missed.
Those 90 days of paystubs matter because they establish your baseline. Every wage-loss system starts from the same place, your earnings before the injury. Compensation programs calculate benefits from your average pre-injury earnings, as Colorado’s workers’ compensation division describes for injured workers, and a car accident claim uses similar logic. If the insurer cannot see what you normally made, it may lowball what you lost.
Your employer contact information matters because I will need a person in payroll or human resources who can verify your dates and income on company letterhead. And your PTO record matters because using earned leave to cover a crash-related absence is still a loss, one that people routinely forget to claim. Pull these together before you do anything else. If you were paid partly in cash or work more than one job, collect the deposit records and paystubs from every income source, because your claim has to reflect everything you actually earned, not just your main W-2.
Step 1: Ask Your Employer for a Written Verification Letter
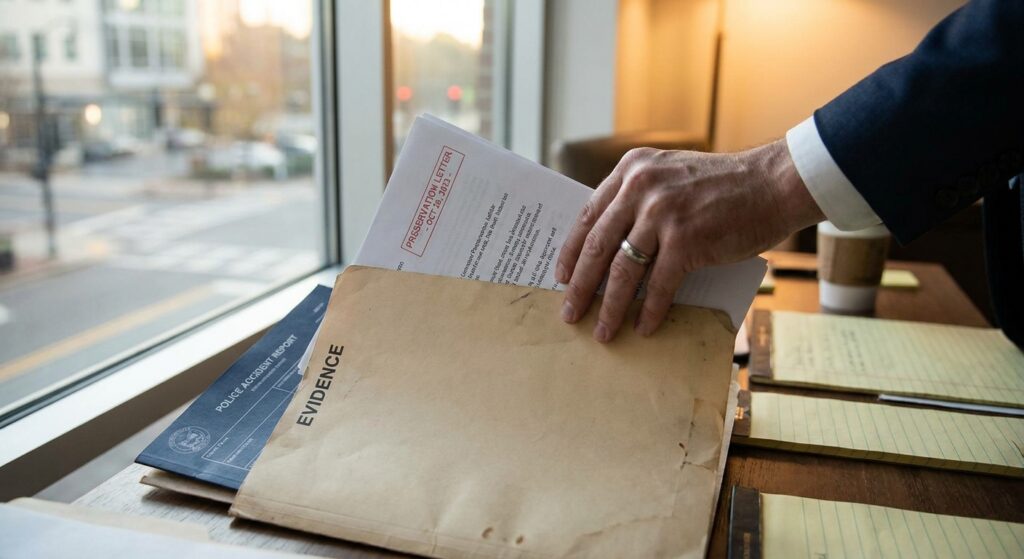
Request a written verification letter from your employer, on company letterhead, that states your hire date, your hourly rate or salary, your normal work schedule, the exact dates you missed or worked reduced hours, and the total income you lost.
The letterhead is not a formality. A letter on official company stationery, signed by someone in payroll or human resources, carries more weight with an adjuster than a note you typed yourself. It tells the insurer that a neutral third party, your employer, is standing behind the numbers. A handwritten estimate invites doubt. A formal letter closes the door on it.
Be specific about what you ask for. Do not just request “a letter about my time off.” Tell your employer the letter needs your dates of employment, your rate of pay, your usual hours, and a day-by-day or period-by-period breakdown of what you missed and what that cost. If you were on reduced hours or light duty for part of the recovery, that has to be in there too, because partial wage loss is still wage loss. When I handle this for a client at Carma Legal, I draft exactly what the letter needs to say and send it to the employer, so the document comes back complete the first time and I am not chasing corrections weeks later.
Step 2: Use Your Paystubs to Set Your Baseline Weekly Earnings
Use your paystubs from the 90 days before the crash to calculate your average weekly earnings. That baseline is what the entire lost wages claim is measured against.
If your income is steady, this is simple math. If your hours or commissions fluctuate, add up your gross earnings over that 90-day window and divide to get a reliable weekly average. That average absorbs the good weeks and the slow weeks and gives the adjuster a fair, defensible number instead of a cherry-picked figure either side could argue about.
If you work more than one job, do this for each source and add the weekly totals together. Your loss is the sum of everything you could not earn, not just your primary paycheck. The same goes for anyone paid partly in cash or through deposits that do not show up on a traditional pay stub, where bank statements and deposit records fill that gap. I have seen claimants leave real money on the table simply because they only handed the adjuster the paystubs from their main job and forgot the second one. Every dollar you lost belongs in the calculation, and documenting all of it up front keeps the insurer from later claiming you exaggerated.
Step 3: How Do You Prove Lost Income If You Are Self-Employed?
If you are self-employed, you prove lost income with profit-and-loss statements, bank deposit records, tax returns, and a letter from your CPA or bookkeeper showing what you earned in comparable periods before the crash and what you lost while you could not work.
Self-employment income may be recoverable in North Carolina. The state’s civil jury instructions recognize lost earnings as a category of damages, and courts have allowed recovery based on documented business records even when income rises and falls month to month. The key word is documented. An adjuster will not take your word that a strong month was coming. Records make the difference.
The comparison approach works best. Show what your business brought in during the same weeks last year, or the months right before the collision, then show the drop during your recovery. A short letter from your accountant tying those numbers together turns a pile of statements into a clear, credible story about what the injury cost your business. If you missed jobs, cancelled contracts, or turned away work, keep that correspondence too. I walk self-employed Carma Legal clients through exactly which records to pull and how to present them, because a fluctuating income is not a weakness in your claim, it just has to be proven with more care than a fixed salary does.
Step 4: Does Using Your PTO Still Count as a Loss?
Yes. If you used paid time off or sick leave to cover the days you missed, you may still have a lost wages claim. That PTO is part of your compensation package, and being forced to spend it because of someone else’s negligence can be a real economic loss.
People assume that because they still got a paycheck, they lost nothing. That is not how it works. You earned that leave. You would otherwise have banked it, used it for a vacation, or saved it for a day you actually chose to take off. The crash forced you to burn a benefit you had already worked for, and North Carolina law may treat that exhaustion of earned leave as an out-of-pocket loss, not a freebie the insurer gets to ignore.
So keep a clean record of every PTO hour and every sick day you spent on crash-related absence or medical appointments, and include it in the employer letter. Do not let the adjuster wave it off with “but you were paid.” The right answer is that you paid, out of benefits you owned, and the at-fault driver’s insurer may owe that back to you. I make sure that leave shows up as its own line in the demand Carma Legal sends, because it is money most claimants never even think to ask for.
Step 5: Handle Reduced Hours, Partial Days, and Shift Differentials
Document the smaller, less obvious losses too: partial shifts you had to leave early, overtime you could no longer work, and premium pay you missed. These add up, and they are easy to overlook.
Charlotte claimants often work in banking, healthcare, and the skilled trades, where income includes shift differentials, quarterly bonuses, and commission structures that never appear on a simple base-pay stub. If you normally pull a night differential, weekend premium, or regular overtime, and your injury knocked you off those shifts, that lost premium may be part of your claim. So is a quarterly bonus you would have hit if you had not been out for three weeks.
An adjuster who does not know your industry may value your loss off your base rate alone and quietly ignore everything else. That is where knowing the local area matters. Having handled injury files in Mecklenburg County for Carma Legal, I know which documentation adjusters and juries expect to see when verifying these less obvious income sources, and I know to ask for it before it becomes a fight. When you worked reduced hours or light duty during part of your recovery, the difference between your normal earnings and your reduced earnings may be recoverable too. The goal is to capture the full shape of what you actually would have earned, not a stripped-down version of it.
Step 6: What If Your Doctor Keeps You Out Longer Than Expected?
If your physician extends your work restrictions or you need more treatment than anyone first predicted, request an updated employer letter showing the additional missed dates and income, then revise your demand before the insurer closes the file.
Recovery rarely follows a tidy schedule, and honestly, the length of that timeline is what surprises most clients. In North Carolina, we usually do not begin negotiating until you have found out the full extent of your injuries and either resolved them or reached maximum medical improvement. Your orthopedist may extend restrictions, your physical therapist may add weeks, or a symptom that seemed minor may turn out to need more care. When that happens, your lost wages claim has to grow with it. The mistake is submitting a wage figure based on the original estimate and then never updating it once you end up out longer.
This is one of the clearest reasons to have an attorney who personally manages your file instead of a case manager juggling hundreds of them. I keep track of your treatment timeline at Carma Legal, so when your return-to-work date moves, I know to go back to your employer for updated numbers and to revise the demand before the insurer treats the claim as final. Timing is everything here. Once an adjuster considers a file closed, reopening it to add wage loss is an uphill fight. Staying ahead of that, and keeping the documentation current as your treatment unfolds, is exactly the kind of hands-on management that gets missed when clients become file numbers.
Step 7: Send the Lost Wages Demand the Day You Return to Work
Present your lost wages demand with all supporting records the moment your physician releases you to return to work. That is the point when your loss is complete and provable, and it is the point when the insurer should see the full, documented number.
By then you have your baseline paystubs, your employer verification letter with exact dates, your PTO record, any self-employment records, and your medical release confirming you were kept out for a medical reason. Submitting all of it together, as one clean package, gives the adjuster nothing to nitpick and no room to claim the loss was vague or unproven.
This is where direct attorney access can change the outcome. When my Carma Legal clients call, they speak to me, the attorney, not just staff, and I walk them through each of these steps so they are not guessing about what to send or when. You see my face on the website and you hear my voice when you call in, because I run a smaller firm intentionally so I can stay boots on the ground throughout your claim, including when we gather pay records and employer statements for the demand. My job is to reduce your stress, help you get the care you need, and pursue the compensation you may be owed. Whether you are recovering from a crash here in Charlotte or working with our Mesa office, the process is the same: prepared from the beginning, honest guidance the whole way through.
What Happens If the Insurer Disputes Your Lost Wages Claim?
If the insurer disputes your lost wages, the answer is not to simply argue back and forth over a number. The answer is evidence: comparable results, thorough records, and a willingness to keep pushing until the offer is fair.
I had one Carma Legal client who received a lowball offer on the overall claim. Instead of just demanding more money, I pushed back with legal research and data-driven evidence, including jury verdicts and settlements from similar cases in the same county. That moved the offer up. It still did not fairly compensate my client in my view, so we kept pushing and took the case to mediation, where we secured an offer that exceeded my client’s expectations in that particular case. Comparable-case data changes the conversation. It turns an arbitrary haggle over numbers into a discussion about what the insurer could realistically face in front of a jury.
I refused to compromise on what I believed that claim was worth, and that includes the wage-loss portion. If the adjuster claims your income was too irregular to prove, or that your time off was longer than the injury justified, the response is documentation and comparables, not frustration. Carma Legal handles injury cases on a contingency fee, so there is no fee unless we recover for you, and the first consultation is free. That means you can sit down and go through your lost income documentation before you ever decide whether to hire me.
The Outcome: Reimbursement for Every Day You Could Not Work
When you follow these steps and submit complete employer verification, paystubs, and your medical release early in the claim, you put the at-fault driver’s insurer in the position of considering reimbursement for the income you were unable to earn while treating your injuries. That is the outcome a well-built wage claim is designed to pursue.
Timing still governs everything. North Carolina generally gives you three years from the date of the collision to file a negligence lawsuit, but your lost wages documentation should be submitted long before that deadline, ideally within weeks of your return to work, so the adjuster values your claim correctly from the start. The statute of limitations protects your right to sue. It does not protect a wage claim you documented too late to be taken seriously.
The woman who texted me from that CVS parking lot did not have to choose between her paycheck and her doctor’s orders. We at Carma Legal documented every missed day, sent the employer letter early, and put her wage loss in the demand from the beginning, so the adjuster never got the chance to call it “hard to prove.” That is what preparation from day one buys you: control over your own claim while you focus on healing.
Call Carma Legal today for a free consultation to review your pay records, employer documentation, and medical release, and to discuss whether your lost wages claim is being valued correctly by the at-fault driver’s insurer. When you call, you reach me, the attorney handling your case, at 702-934-2228.
Frequently Asked Questions
Can I recover lost wages if I used my own sick days to cover the time off?
Yes. Using PTO or sick leave can be a compensable loss. You exhausted benefits you had already earned and would otherwise have saved or used at your own discretion. Keep a record of every hour of leave you spent on crash-related absences and include it in your employer letter.
What if I am self-employed and my income varies every month?
You may still be able to recover lost income. Provide profit-and-loss statements, bank deposit records, tax returns, and a CPA or bookkeeper letter showing your earnings in comparable periods before the crash. Fluctuating income is not a barrier, it just has to be proven with records rather than a single pay stub.
Do I need a lawyer to file a lost wages claim, or can I send the documents to the adjuster myself?
You can submit the documents yourself. The difference an attorney makes is knowing when to request them, how to present them in the opening demand, and how to push back when the insurer disputes the amount. Getting the sequence and the timing right is what can protect the value of that part of your claim.
What happens if my doctor keeps me out of work longer than the adjuster expected?
Request an updated employer letter showing the additional missed dates and income, then submit a revised demand before the insurer closes the file. Your wage claim should grow with your treatment. The mistake is locking in an early estimate and never updating it once you end up out longer.
How long do I have to file a lost wages claim after a Charlotte car accident?
North Carolina generally gives you three years from the date of the crash to file a negligence lawsuit. But you should document and submit your lost wages within weeks of returning to work, so the adjuster values your claim correctly from the start rather than treating it as a late addition.
Can I recover lost income if I am paid in cash or work multiple jobs?
Yes. Provide paystubs or bank deposit records from every income source and calculate your average weekly earnings across all of them. Your loss is the total of everything you could not earn, so leaving out a second job or cash income only shortchanges your own claim.
Let the Evidence Do the Talking
If you’re wondering whether your documentation is strong enough to prove lost income, or if you’re unsure what types of wage losses actually qualify after your accident, an experienced attorney can review your situation and identify every dollar you’re entitled to recover. Carma Legal helps Charlotte and Mesa clients build compelling lost wages claims that insurance companies take seriously.
Individual results vary and depend on each case’s unique facts, injuries, liability, and other factors. Past outcomes do not predict future results.